Advertisement
Advertisement
Dubai’s commercial real estate sector continued its upward trajectory through 2025, with office values across key business districts recording strong growth. Leading the trend, Downtown Dubai saw average office sale prices climb to around Dh5,130 per square foot, marking a significant increase compared to the previous year and reinforcing the area’s position as one of the city’s most sought-after business hubs.
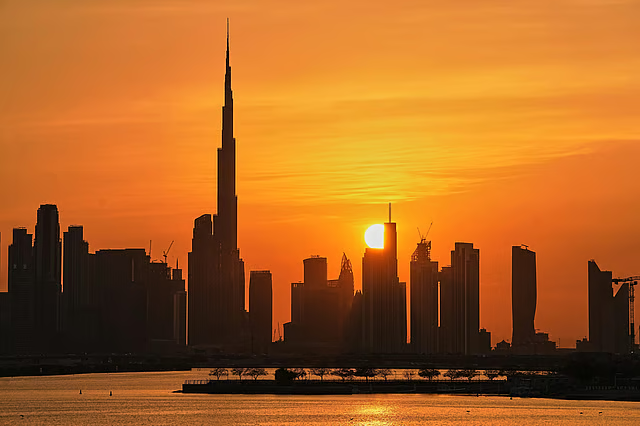
The rise in pricing has been accompanied by a sharp increase in high-value transactions. Large office deals exceeding Dh10 million more than doubled over the past year, highlighting sustained interest from investors seeking stable, income-generating assets in established locations. Market observers note that this trend reflects growing confidence in Dubai’s long-term economic outlook and its appeal as a regional business center.
Demand for premium office space remains a key driver of this growth. Companies are increasingly prioritising modern, efficient layouts in well-connected locations, particularly buildings with direct access to public transport and strong surrounding amenities. These features continue to command higher rents and valuations, as occupiers place greater emphasis on workplace quality and accessibility.
Occupancy levels across prime office buildings remain high, with limited availability in top-tier properties. As demand continues to exceed supply, both rental rates and capital values have shown consistent increases over recent years. This pattern has been especially evident in central districts, where high-quality assets are operating close to full capacity.
Sector-specific demand has also played an important role in shaping the market. Financial services and technology firms have emerged as leading contributors, accounting for a substantial share of office space uptake. These industries are typically concentrated in grade-A developments, further supporting price growth in core business locations.
Looking ahead, a substantial pipeline of new office space is expected to enter the market between 2026 and 2030. Key areas such as Business Bay, Meydan City, DIFC and Jumeirah Lake Towers are set to see the majority of upcoming developments. While this additional supply may gradually ease pressure on availability, current conditions suggest that demand will continue to absorb new inventory in the near term.
Market attention is now focused on how future supply will influence pricing trends. In the short term, however, the outlook remains stable, with strong demand expected to sustain current momentum. High-quality, well-managed buildings are likely to remain the top choice for occupiers and investors, while a widening gap between premium and secondary properties may become more pronounced.
Overall, Dubai’s office market continues to demonstrate resilience and growth, driven by a combination of strong demand, limited availability, and sustained investor confidence in the city’s economic fundamentals.
 Watch AD
Advertisement
Advertisement
Advertisement


 Recommend


